For capital gains on a home sale in Crown Point, the first question is whether the federal exclusion covers your gain. Internal Revenue Service (IRS) Topic 701 says you may exclude up to $250,000 of gain on the sale of your main home, or up to $500,000 on a joint return, if you meet the ownership and use tests. At our Crown Point shop we pull your purchase papers and improvement receipts before we list, so you and your tax preparer start with real numbers.
We’re the shop on South Main in Crown Point. Love Thy Neighbor. Call (219) 801-0432.
Thinking about selling before or after New Year’s? Call (219) 801-0432 and we will walk the timing with you. Curious what nearby homes sold for? Search homes for sale. You can see homes for sale and sold homes across Indiana and Illinois there.
This is how our shop handles the tax side of a sale for sellers in Crown Point and the Northwest Indiana towns we work, plus what the IRS publishes. We are Realtors, not tax preparers. Take your numbers to yours. Start the seller path on Sell. More selling guides are on Learn: Selling. Short questions go to Ask Realest.
The exclusion and the two tests
IRS Topic 701 sets out the ownership test and the use test. You meet the ownership test if you owned the home for at least 24 months out of the 5 years before the date of sale. You meet the use test if you lived in it as your home for at least 24 months of those 5 years.
Topic 701 says the two 24-month stretches can be different periods, as long as both fall inside the 5 years that end on the sale date. On a joint return, either spouse can meet the ownership test, and both spouses have to meet the use test.
Topic 701 also says you generally can’t take the exclusion if you excluded gain on another home sale during the 2 years before this one. And Publication 523 says a home you got through a like-kind exchange in the past 5 years doesn’t qualify.
Short of 24 months? Publication 523 says you may still get a partial exclusion if the main reason for the sale was a change in workplace, a health issue, or an unforeseeable event. For a work move, the new job has to be at least 50 miles farther from the home than the old one.
Why year-end timing matters
The tests count back from the date of sale. Publication 523 says that date is in box 1 of Form 1099-S if you get one. If you don’t, it is the earlier of the day title transfers or the day the burdens and benefits of ownership shift to the buyer.
So the closing date does two jobs. It sets which tax year the sale belongs to. It can also decide whether you reach 24 months. If your second anniversary of moving in lands in December or January, put that date in front of us before we pick a closing date.
The full Publication 523 on IRS.gov when we checked on October 26, 2026 was the edition for 2025 returns. Topic 701 was updated October 12, 2026. Ask your tax preparer what applies to your 2026 return.
How gain is figured
Publication 523 lays it out in two steps. First, selling price minus selling expenses gives the amount realized. Then, amount realized minus your adjusted basis gives the gain or loss.
Selling expenses. Publication 523 lists sales commissions, advertising fees, legal fees, and mortgage points or other loan charges you paid that would normally be the buyer’s, plus other costs to sell. Publication 936 says points a seller pays for the buyer’s loan are a selling expense too.
Basis. That starts with what you paid. You add certain settlement costs from your purchase, such as recording fees, survey fees, transfer taxes, and owner’s title insurance. Then you add improvements that are still part of the home.
Improvements, not repairs. Publication 523 says improvements add to the value of your home, prolong its useful life, or adapt it to new uses. Its examples include additions, a new roof, new siding, a furnace, central air, a water heater, kitchen modernization, a driveway, and a fence. It leaves out repairs that only keep the home in good condition, like painting, fixing leaks, or replacing broken hardware, and improvements you later tore out.
A loss. If the math comes out negative, Publication 523 says you can’t deduct the loss on your main home.
Business or rental use. If you rented the home or used part of it for business, Publication 523 has separate rules, including depreciation you may have to recapture. Bring that to your preparer early.
Held more than a year. IRS Topic 409 says gain on an asset you held more than one year is generally long-term, and one year or less is short-term.
Want us to pull your numbers together before you list? Call our shop at (219) 801-0432. We answer the phone on South Main. Or check recent sales nearby first: Search homes for sale.
Form 1099-S at the closing table
The Form 1099-S instructions say the person responsible for closing the sale files Form 1099-S. When a Closing Disclosure is used, that is the settlement agent listed on it.
The instructions list an exception for a main home sold for $250,000 or less, or $500,000 or less if the seller is married. The seller gives written certification, signed under penalties of perjury, that the home is the main home and the full gain is excludable. Joint sellers each certify, or the closing agent files for the seller who does not.
If you do get a 1099-S, Topic 701 says you must report the sale even if the gain is excludable. Publication 523 says that goes on Form 8949. We tell sellers to expect the certification question from the title company and to answer it with their preparer’s help.
Indiana starts from the federal number
Under Indiana Code 6-3-1-3.5, Indiana adjusted gross income for individuals starts with federal adjusted gross income under Section 62 of the Internal Revenue Code, then makes Indiana’s own changes. Ask your preparer how your sale flows through your Indiana return.
Moving to a new home in Lake or Porter County after the sale? The homestead deduction is a separate county filing. Our Indiana Homestead Deduction page has the steps.
How we prepare a seller for the tax side
1. Find the purchase papers. We ask for the Closing Disclosure or settlement statement from when you bought, plus the deed. Publication 523 says to keep basis records until 3 years after the due date of your return for the year you sell.
2. List the improvements. Write down every roof, furnace, siding, kitchen or fence job, with the date and the receipt. We use the same list when we price the home. See How to read a comparative market analysis before you list and What to fix before you list.
3. Check the calendar. Your move-in date, your purchase date, and any 24-month mark go next to the closing date we target.
4. Run a net sheet. Price, selling expenses, payoff, and closing costs on one page. Use our seller net sheet answer. Then read Listing Agreements With Our Crown Point Shop.
5. Bring your preparer in before you sign. We share the numbers you approve. The tax answer is theirs.
6. Keep the closing papers. Your sale Closing Disclosure and any 1099-S go in the same folder for April.
Selling a home by town
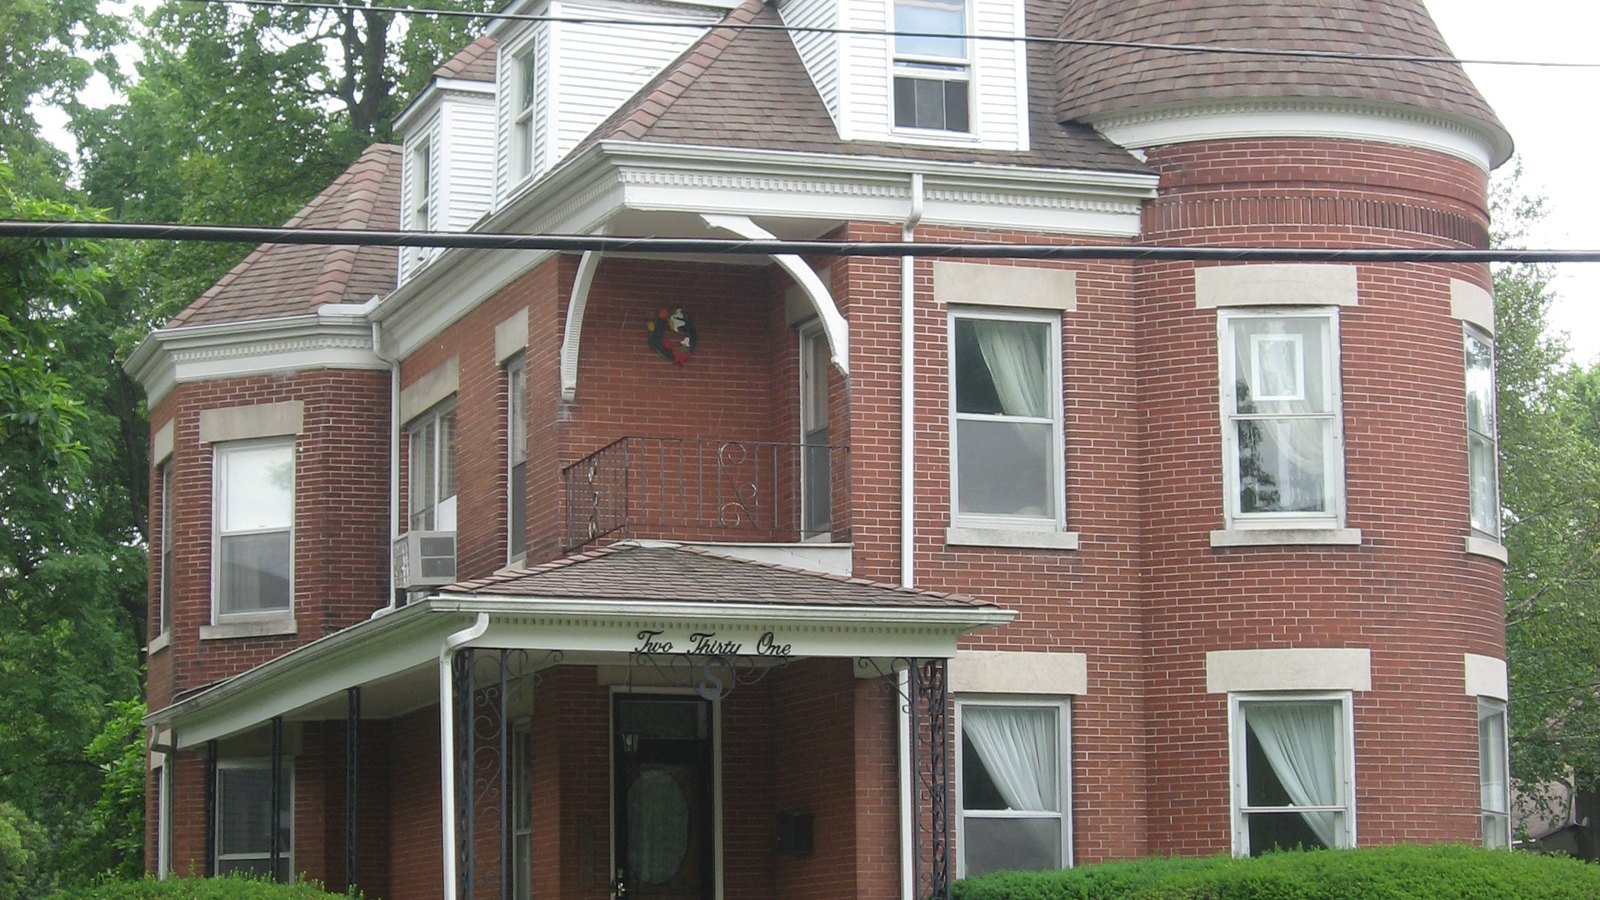
The IRS tests are the same in every town. The sale price and the improvements are not. Sellers come to us for Crown Point, St. John, Schererville, Dyer, Munster, Highland, Cedar Lake, Lowell, Merrillville, Hobart, and Valparaiso. The lead photo is a house in Crown Point’s Sunny-side historic district.
For what living there is like, Real Estate USA keeps guides to homes in Crown Point, St. John, Schererville, Dyer, Munster, Highland, Cedar Lake, Lowell, Merrillville, Hobart, and Valparaiso. It also has Buy first or sell first in Northwest Indiana, What to do before you list, How to price a home for sale, and Moving to Crown Point, Indiana.
The tradeoffs to weigh
December closing or January closing. The date of sale sets the tax year and the end of your 5-year look-back. Ask your preparer which year fits your return.
Selling now or after the 24-month mark. Waiting can bring you inside the tests. It also means carrying the home longer. We can show you what the market did nearby while you decide.
Fix it or price it. Under Publication 523, improvements count toward basis and plain repairs do not. That is one input. What the buyer will pay is another. Read our price reductions guide and our seller concessions guide.
Buying your next home at the same time. That means two closings on two calendars. Read Buy and sell at the same time and Downsizing in Northwest Indiana. Selling in a divorce, an estate, or a senior move has its own pages: divorce, probate, and senior move.
What we will ask you back
Expect questions about when you bought, when you moved in, what you have improved, whether you ever rented the home or used part of it for work, and who prepares your taxes. Buying next? Start on Buy. Ready to talk? Use our contact page or call (219) 801-0432.
Questions about capital gains on a home sale in Crown Point
Do I pay capital gains tax when I sell my house in Indiana?
Not on gain the federal exclusion covers. IRS Topic 701 says you may exclude up to $250,000 of gain on the sale of your main home, or up to $500,000 on a joint return, if you meet the ownership and use tests. Ask your tax preparer. Call us at (219) 801-0432. We are licensed in Indiana and Illinois.
What are the ownership and use tests for selling a home?
IRS Topic 701 says you must have owned the home and lived in it as your home for at least 24 months each in the 5 years before the sale. The two periods can be different, but both have to fall inside those 5 years.
What if I have not lived in my house for two years?
IRS Publication 523 says you may still get a partial exclusion if the main reason for the sale was a change in workplace, a health issue, or an unforeseeable event. A work move counts when the new job is at least 50 miles farther from the home than the old one.
Will I get a Form 1099-S when I sell my home?
Maybe. The IRS Form 1099-S instructions say the closing agent files it, with an exception for a main home sold for $250,000 or less, or $500,000 or less if married, when the seller signs a written certification. If you get one, Topic 701 says you must report the sale.
What can I add to my home’s basis before I sell?
IRS Publication 523 says you add improvements still part of the home, such as a new roof, a furnace, siding, or a kitchen modernization, plus certain purchase settlement costs. Repairs like painting or fixing leaks do not count. Keep the receipts.
How do I start selling my home with Realest?
Call (219) 801-0432 or email saso@realest.com. Visit us at 112 S. Main St., Suite B, Crown Point, IN 46307. Bring your purchase Closing Disclosure, a list of improvements, and your tax preparer’s name if you have one. Love Thy Neighbor.
Talk to the shop
Realest, 112 S. Main St., Suite B, Crown Point, IN 46307
(219) 801-0432 | saso@realest.com
Love Thy Neighbor
Top photo: Sunny-side Historic Residential District, Crown Point, April 2015 by Chris Light, CC BY-SA 4.0, via Wikimedia Commons. Cropped.
Next reads: Sell, Learn: Selling, Seller net sheet, Listing agreement shop, Reading a comparative market analysis, Crown Point hub. Homes for sale and sold homes in Indiana and Illinois: Search homes for sale.
Sources
- IRS Topic 701, Sale of Your Home (updated Oct 12, 2026): $250,000 and $500,000 exclusion, ownership and use tests, 2-year rule, reporting
- IRS Publication 523, Selling Your Home (for 2025 returns): date of sale, disqualifications, partial exclusion, gain, basis, improvements, records
- IRS Publication 936 (for 2025 returns): seller-paid points as a selling expense
- IRS Topic 409, Capital Gains and Losses: long-term and short-term
- IRS Instructions for Form 1099-S (revised December 2026): who files, principal residence exception and certification
- Indiana Code 6-3-1-3.5, adjusted gross income (official PDF, Indiana General Assembly, 2026)
This page is shop process, not tax, legal, or accounting advice. Your tax preparer and your closing documents have the final word.
Related Posts
Assumable Mortgage in Crown Point: What Sellers Should Know
An assumable mortgage in Crown Point lets a qualified buyer take over…
Termite Inspection in Crown Point: What Home Buyers Should Know
A termite inspection in Crown Point is a separate look at a…
Mortgage Payoff When You Sell in Crown Point: What Sellers Should Know
For a mortgage payoff when you sell in Crown Point, the number…